Chapter 2
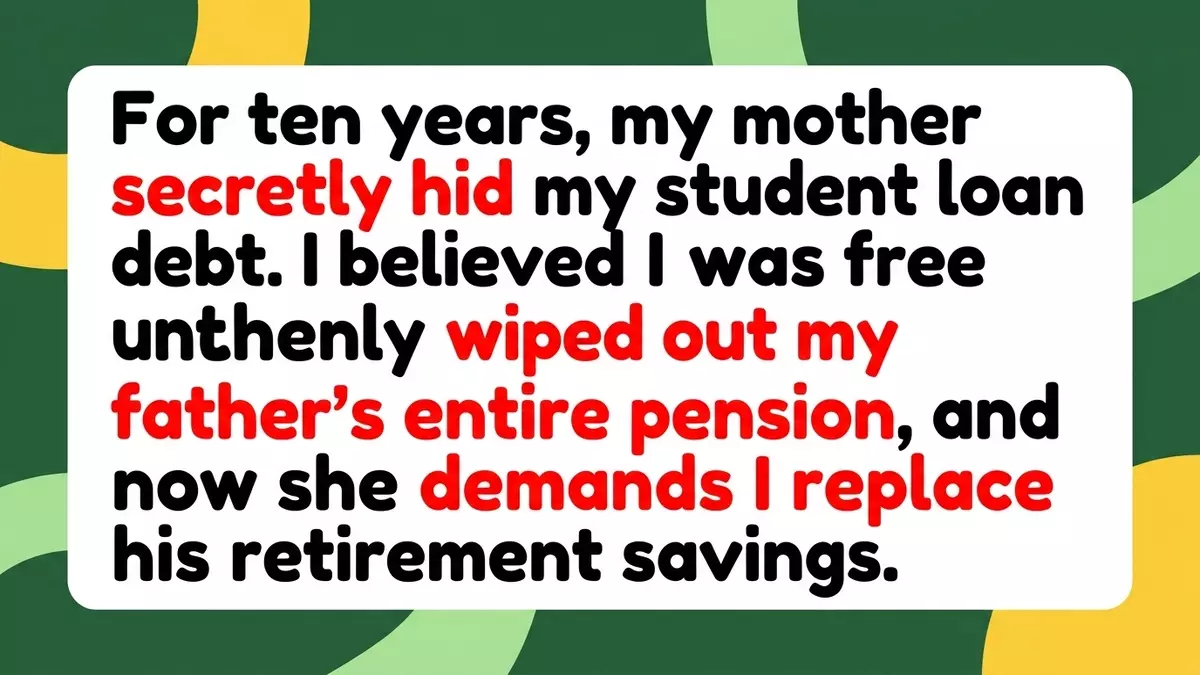
The Pension Invalidation: When the lending agency finally caught up with the family, the accumulated debt completely wiped out the father's entire lifetime pension, leaving him with absolutely nothing.
A Lack of Agency: By keeping the debt a secret, the parents completely denied the son the opportunity to tackle the principal amount early in his career, crossing the line into what financial psychologists classify as financial abuse.
A Cultural and Practical Divide in the Online Community
Seeking perspective on whether he was morally obligated to replace his father's wiped-out retirement fund, the son shared his nightmare scenario online. The viral post split the internet community down deeply cultural and practical lines.
Western Autonomy vs. Filial Obligation
The Reddit community engaged in a fierce debate regarding where the moral responsibility truly lay in this multi-generational conflict:
-
The Western Perspective: Many commenters from individualistic cultures declared the son completely in the right for protecting his hard-earned savings. They argued that because the parents actively lied and engaged in systemic deception, they must bear the consequences of their financial irresponsibility.
-
The Collectivist Reality: Users from similar cultural backgrounds in Asia pointed out the heavy social cost of walking away. In these communities, failing to bail out elderly parents—regardless of their mistakes—can permanently damage a person's social standing, invite intense family shunning, and sever vital community ties.
-
The Educational Benefit: A vocal segment of the audience argued that since the loan directly funded the degree that launched the son's successful career, he bore a practical responsibility to ensure the base amount was resolved, separate from his mother's drama.
Breaking the Generational Debt Cycle Safely
Navigating familial duty when it is tangled in a web of financial deception is an emotional minefield. However, bailing out parents who refuse to practice basic accountability often only enables future disasters. To protect his own future without completely abandoning his moral values, the son must learn to separate emotional manipulation from mathematical reality.
Practical Steps for Financial Protection
Instead of handing a lump sum of cash directly to his mother—which risks being absorbed by her ongoing failed business ventures—the son can choose actionable, controlled methods of assistance:
-
Pay the Principal Directly: Offer a strict compromise by paying the original principal amount of the college debt directly to the lending agency, completely bypassing the mother's hands.
-
Establish a Controlled Allowance: If choosing to assist his father, the son can pay for specific, vital expenses (like medical bills or groceries) directly to the providers, ensuring his hard-earned money is never mismanaged.